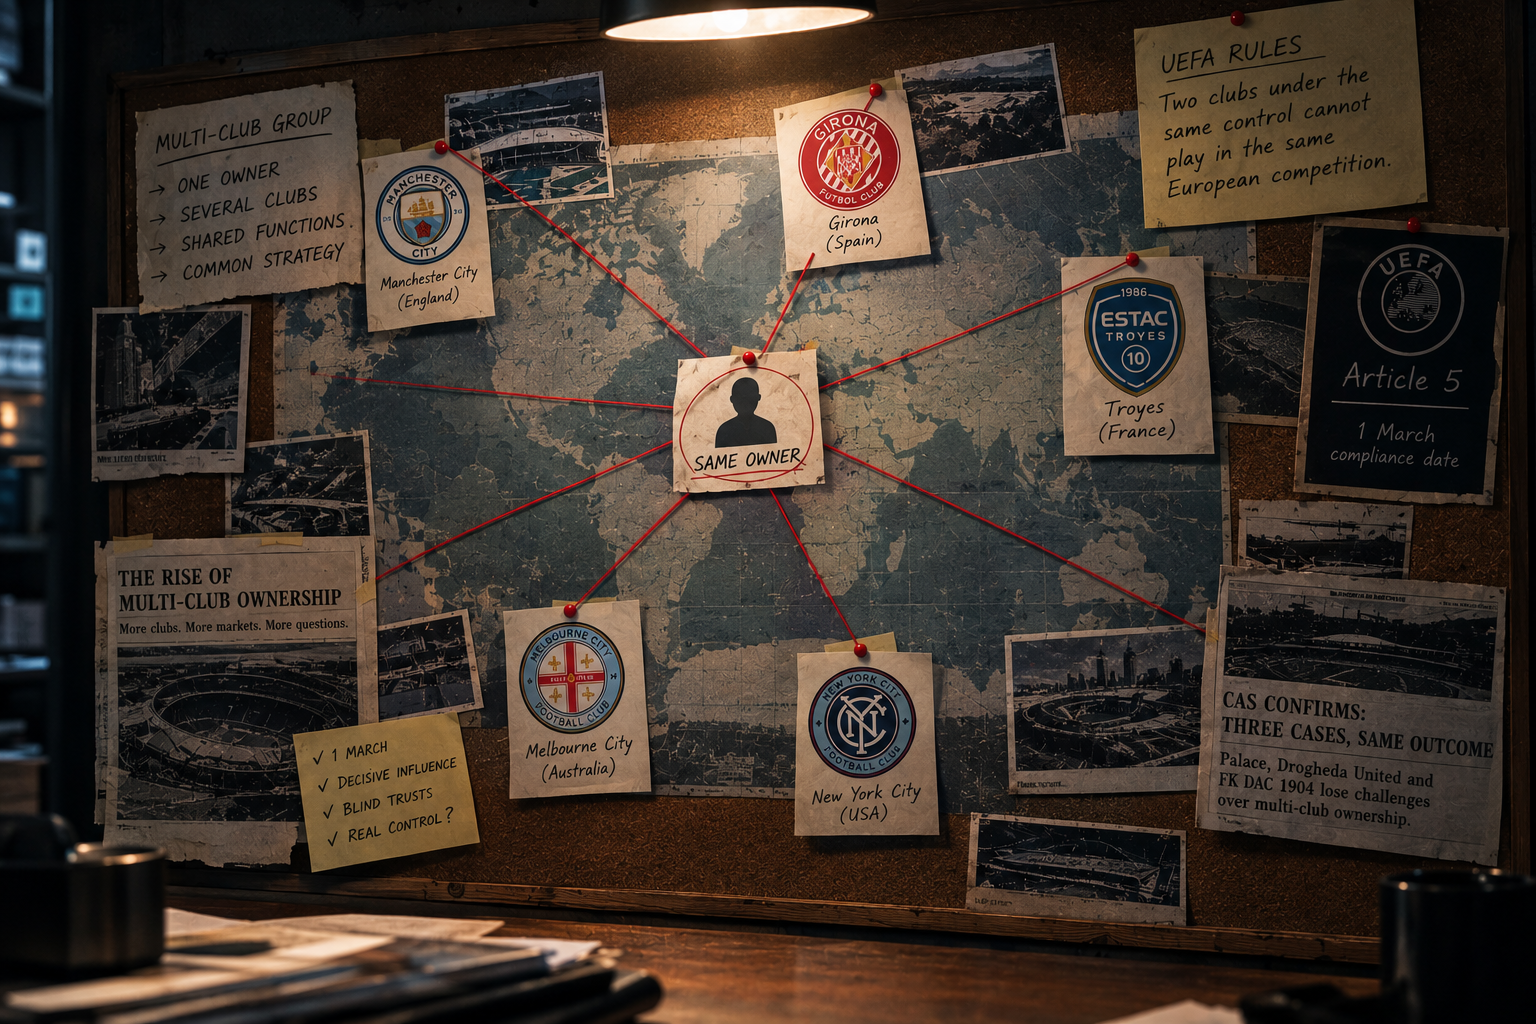
What a multi-club group is for
Strip away the language and a multi-club structure is a portfolio. One owner, several clubs in several countries, managed with shared functions and a common strategy. The model spread because it solves problems that a single club cannot solve alone — and it creates others that only appear later.
What a group is for, and what it costs the club inside it
Strip away the language and a multi-club structure is a portfolio: one owner, several clubs, shared functions, a common strategy.
What the group gains
What the individual club gives up
That last line is the whole subject of what follows, and it is the part nobody anticipates until it happens to them.
The rule itself
Article 5 of UEFA's club competition regulations exists to protect one thing: the credibility of a match between two clubs that might answer to the same person. It states that no club taking part in a UEFA competition may, directly or indirectly, hold or deal in the shares of another participating club, be a member of one, be involved in any capacity in the management, administration or sporting performance of one, or hold any power over any of those things.
The operative concept is decisive influence, and in practice a shareholding above thirty percent in two clubs in the same competition is treated as crossing the line.
The rule does not prohibit owning several clubs. It prohibits two of them meeting in the same competition while under common control.
Most groups never trigger it. The ones that do discover the machinery all at once. When two clubs in a group do qualify for the same competition and nothing has been done about it, the tie-break is mechanical: the club with the better sporting ranking keeps its place, and the other is moved down to a lower competition or excluded altogether.
How Article 5 is applied
The rule is simple in structure. What makes it brutal is the timing of the second question, which has to be answered before anyone knows the answer to the first.
Do two clubs in the group qualify for the same UEFA competition?
No issue arises
Article 5 is not engaged, whatever the group owns.
Was the conflict already resolved on 1 March?
Shares sold, placed in a blind trust, or voting rights and board seats given up — before that date.
Both clubs play
The remedy must stay in place until the end of the competition.
One club loses its place
The better-ranked club stays. The other is moved to a lower competition, or excluded.
Everything is judged on the situation as it stood on 1 March — not on the day the club qualified.
Why the date is the whole problem
Compliance is fixed at 1 March of the season before the competition, and the club must stay compliant from that date through to the end of the competition. A group therefore has to resolve hypothetical conflicts — situations that may never arise — months in advance, and to do so definitively.
UEFA briefly looked ready to soften this. In October 2025 a dual-deadline system was floated: clubs would flag a potential conflict by 1 March but would have until early June to resolve it, once qualification was actually settled. It would have removed most of the injustice. On 8 December 2025, a UEFA circular confirmed that no substantial change would be made and that 1 March remains binding for 2026/27.
The practical consequence is that the compliance work happens in January and February, on scenarios rather than facts. A club sitting twelfth in its league in February must still act as though it might win a cup — because if it does, and nothing was done, the trophy is worth less than it looked.
Blind trusts, and what they actually achieve
The standard remedy is a blind trust. City Football Group used one for Girona, INEOS for Nice and later for Lausanne-Sport. The mechanism works, but two misconceptions about it have proved expensive.
The first is that UEFA approves them. It does not. When clubs argued before the Court of Arbitration for Sport that certain trusts had been accepted by the regulator, the panels replied that UEFA's Club Financial Control Body had never assessed or approved any such arrangement. A trust is a step a group takes at its own risk, not a certificate it obtains.
The second is that a trust can be set up late. Trusts allowed after the deadline in 2024/25 were an explicit, one-off exception, described as such at the time and not renewed. The arrangement has to exist before 1 March and to run for a long period — for the 2026/27 season, from March 2026 until the middle of 2027.
And the cost is real. An owner in a blind trust cannot appoint the manager, cannot approve a transfer, cannot inject money when the club needs it. Groups increasingly conclude that a permanent separation of assets is cheaper than a temporary surrender of control.
Worked example — Crystal Palace, 2025
John Textor, through Eagle Football, held around 43% of Crystal Palace and controlled Lyon. On 1 March 2025, Palace sat twelfth in the Premier League. Nothing was done, and on any reasonable reading nothing seemed necessary.
| Date | What happened |
|---|---|
| 17 May 2025 | Palace win the FA Cup and qualify for the Europa League. Lyon qualify for the same competition. |
| June 2025 | Textor sells his Palace stake to Woody Johnson — after the assessment date. |
| July 2025 | UEFA's CFCB moves Palace down to the Conference League; Lyon, ranked higher, keeps its place. |
| August 2025 | CAS rejects all three strands of Palace's appeal. Nottingham Forest inherits the Europa League place. |
By the time Palace played, the club genuinely was no longer part of a multi-club group. The shares had gone. It was moved down anyway, because the rule photographs a single day and disregards everything that happens afterwards.
Palace was not an isolated case. The same summer, Drogheda United and FK DAC 1904 lost their own challenges before CAS on the same grounds. Three decisions in one year, all pointing the same way. The case law is now settled, which is exactly why the compliance industry around these structures has grown so quickly.
The regulations are clear and allow no flexibility for a club that was non-compliant on the assessment date.
What this means in practice
For anyone running or advising a group, the 2025 cases redrew the map.
What the 2025 decisions changed for anyone running a group
Three rulings in one year, all pointing the same way. The case law is now settled.
What now has to happen
What no longer works
A second layer is now forming underneath all of this. In England, the new Independent Football Regulator adds statutory oversight of ownership, alongside UEFA's rules rather than in place of them. Several national frameworks are moving the same way. A group that satisfies UEFA may still have to satisfy a domestic authority applying different tests — and neither is obliged to reach the same conclusion.
What the rule does not cover
It is worth being clear about the limits of Article 5, because it is often described as the regulation of multi-club football, which it is not. It governs one narrow question: whether two clubs answering to the same owner can appear in the same European competition. It says nothing about the thing that carries far more money — what happens when one club in a group sells a player to another.
A transfer between two entities with the same ultimate owner is a related-party transaction, and the price is set by people sitting on both sides of the table. That price decides where profit is recognised, which balance sheet carries the asset, and whose regulatory ratios improve. It is the same mechanism described in the piece on player trading, with one difference: the buyer and the seller share an owner. Domestic rules on fair value have started to address it. European ones are still catching up, and the gap between the two is where the serious analysis of multi-club football now sits.